The European beer market is seeing an overall decline in consumption volumes, while new categories are gaining ground. In France, craft breweries continue to multiply, but production conditions are changing under the influence of the climate, regulatory constraints and demand shifting towards segments that were still marginal just a few years ago. This overview of the brewing world deserves a closer look, moving from the surface to less-documented pressures.
Non-alcoholic beer: a rapidly expanding brewing segment
Non-alcoholic beer is attracting growing attention from brewers and distributors. The segment is expanding across most European markets, driven by consumers who are cutting back on alcohol without giving up the ritual of drinking beer. Major brands are investing heavily in their zero-alcohol ranges, with dedicated marketing campaigns.
This growth does not automatically mean that non-alcoholic beers are replacing conventional beers. The two trends—a decline in overall volumes and growth in non-alcoholic beer—are coexisting, with no definitive evidence of a direct substitution effect. Following 75cl news offers a way to see how these changes are reflected in the products available.
For small craft breweries, the picture is more nuanced. Producing high-quality non-alcoholic beer requires specific investment: tighter microbiological controls, filtration or dealcoholization equipment, and more frequent stability testing. The cost of making the transition is holding small producers back from entering this segment. Some opt for contract production or work with specialist partners to overcome these technical barriers.
Climate pressure on hop and malt production
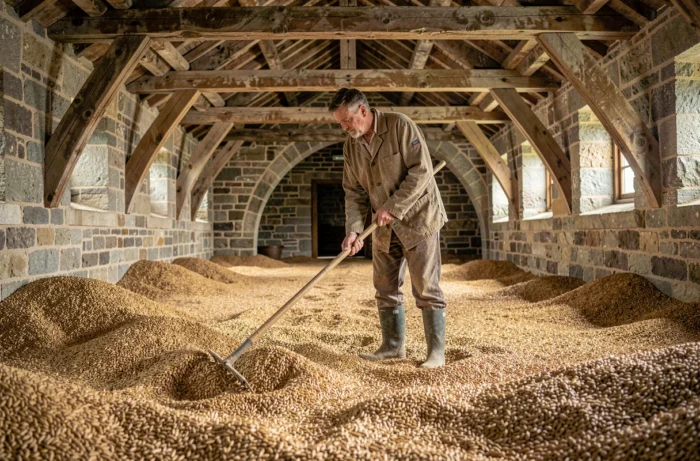
Brewing raw materials are feeling the effects of climate change. Intense heat and irregular rainfall are affecting yields of hops and brewing barley in several European growing regions. Brewers report supply difficulties linked to these conditions, as well as variations in quality from one harvest to the next.
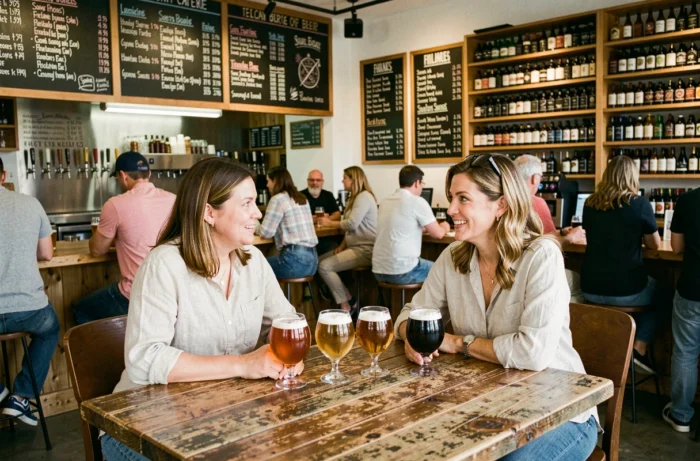
The climate affects both production and sales. Rainy or scorching weekends change attendance at festivals, taprooms and outdoor terraces, weighing on seasonal sales. For craft breweries that rely heavily on direct sales for their revenue, this double exposure—to both raw materials and consumer demand—creates a structural vulnerability.
How brewers are adapting to supply pressures
Brewers facing these pressures are adopting several strategies. Some are diversifying their hop sources by working with local growers or testing varieties that are more drought-resistant. Others are adjusting their recipes to use the malts available rather than trying to preserve exactly the same flavour profile from year to year.
This flexibility is reminiscent of the wine industry’s concept of vintage. Craft beer is beginning to embrace the idea that a batch can vary depending on the harvest, which means educating consumers who are used to consistent flavours.
Craft breweries in France: more breweries, a consolidating market
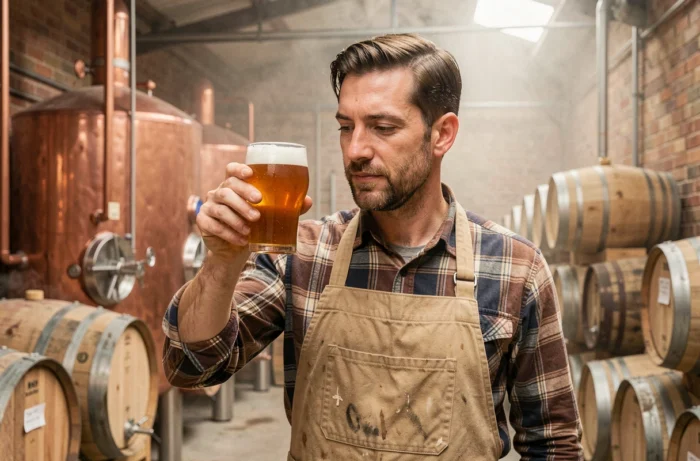
The number of breweries in France has risen sharply in recent years. This growth does not guarantee the long-term survival of every business. The market is showing signs of consolidation: some breweries are closing, while others are merging or joining forces to share distribution and marketing costs.
Product diversification is becoming a key to survival. Breweries that stick to a conventional range (blonde, amber, wheat) are struggling to stand out in a saturated market. Those exploring more distinctive recipes, collaborations between brewers or innovative sales formats (taprooms, online sales, subscriptions) seem better placed to weather the challenges.
- Fruit beers and sour ales appeal to drinkers who do not identify with traditional bitter profiles. Producing them through spontaneous or mixed fermentation requires genuine technical expertise.
- Collaborations between breweries, sometimes across borders, help share production costs and reach new customers through cross-promotion.
- Direct sales in a taproom offer better margins than retail distribution, but come with fixed costs (rent, staff, licence) that are not suitable for every business.
Recycling and sustainability: what is changing in the brewing industry
Responsible practices are no longer just a marketing tool. Managing brewing waste (spent grain, used yeast, process water) is receiving growing attention from brewers and local authorities alike. Spent grain, the solid residue left over from brewing, is finding uses in animal feed, baking and composting.
When it comes to packaging, beer cap recycling highlights an often-overlooked issue. The correct way to sort these small metal items is still not widely understood by the public. Steel caps can be recycled, but their small size causes problems at automated sorting facilities. Some breweries are beginning to provide clear guidance on how to sort their packaging.
Energy and water in the brewing process
Water and energy consumption are major costs for any brewery. Producing one litre of beer takes several litres of water when cleaning and cooling are included. Breweries are investing in heat recovery, treating and reusing rinse water, and installing solar panels to reduce their environmental footprint. These measures remain more accessible to businesses with enough capital to recoup the initial investment.
The brewing world is going through a period in which recipe creativity is coexisting with increasingly tangible economic and environmental constraints. Brewers’ ability to adapt their techniques will determine which businesses make it through the coming years, beyond simply having a talent for creating beers people enjoy.